Most commercial clients require your crew to have commercial carpet cleaning insurance before allowing them to start the job. Property managers, facility managers and general contractors usually ask for a certificate of insurance showing general liability before the first job, and many also require you to name them as additional insured on your policy.
Where you work adds even more risk. An office lobby, a hotel corridor or a restaurant dining room is often open to employees, guests and the public while the carpet is still drying. One damp transition strip can turn a routine maintenance visit into a claim against your company.
When a client’s employee or guest slips, you could be held responsible for the medical bills and any lawsuit. When too much water soaks into the carpet padding, or the wrong solution pulls dye out of an office carpet, the client will expect you to pay for repair or replacement. Even a claim that has no merit has to be answered. General liability usually pays for your legal defense on top of covered settlements, so a lawsuit you win doesn’t drain you of the money your business needs to work.
Common Causes of Carpet Cleaning Claims
Water is a huge part of carpet cleaning, but it also creates risks. OSHA’s walking-working surfaces standard requires workplace floors to be kept clean and, as far as feasible, dry. That’s a hard promise to keep in a building where your crew extracted carpet two hours ago. The EPA advises drying water-damaged areas within 24 to 48 hours to prevent mold, so carpet left wet over a weekend in a closed office is a real exposure.
Here are some situations that can lead to carpet cleaning claims:
Slips at the edges: Watch the spots where damp carpet borders tile: entrances, elevator lobbies, restroom doorways. Hoses run across a hallway trip people too, including your own technicians.
Water that travels Over-wetting can soak padding and subfloor. In a multi-story building it can reach the ceiling of the floor below.
Chemical damage: The wrong product or mix can discolor carpet, rugs and upholstery. OSHA's Hazard Communication standard also requires labels, safety data sheets and training for the chemicals your employees use.
Carbon monoxide from truckmounts:NIOSH warns against running gasoline engines inside buildings or partly enclosed areas and advises keeping power units outside and away from air intakes. A truckmount running in an underground hotel garage, or next to a fresh-air intake, puts the people inside at risk.
Furniture you move: Desks, chairs and display fixtures get moved so you can clean under them. A scratched wall or a monitor that gets dropped off a desk is property damage too.
Get a Carpet Cleaning Insurance Quote Fast
Tell us how many technicians and vans you run and which commercial accounts you service. Only 5 minutes of your valuable time. We can often get same day coverage.
Insurance Coverage Options for Carpet Cleaning Businesses
Most commercial carpet cleaning companies start with general liability and workers’ compensation. Then they add commercial auto insurance for the vans and equipment coverage for their machines, since carpet cleaning companies rely on both vans and machines to get the job done.
General Liability
General liability insurance pays for injuries to other people and damage to their property caused by your work, and it also covers your legal defense costs. Standard limits are $1 million per occurrence and $2 million aggregate. Dropping to $500,000 usually saves less than $100 a year, which doesn’t make much sense when a hotel or property manager’s contract asks for $1 million.
Imagine your crew finishes a job on a Friday night. Your two technicians deep clean the carpet in a fourth-floor conference room, but water gets through a seam near the wall. On Monday the tenant on the floor below finds a stained ceiling tile and a swollen drywall panel. The repair estimate is close to $7,340. That is third-party property damage, the kind of loss general liability is written for, depending on your policy’s terms and deductible.
Damage to the conference room carpet itself is a different situation. Many standard general liability forms exclude damage to the particular part of a property you’re working on when the damage comes from that work. If you shrink or discolor the carpet you’re cleaning, your policy may not pay for it. Ask how your policy handles this before you buy.
Custom Solutions
A one-van operator with three office accounts and a company running four crews under a property management contract don’t need the same policy. We customize your quote to the coverage you need, based on the services you offer, such as commercial carpet, upholstery, tile and grout, area rugs or water extraction, and on the buildings you work in.
Hotels and healthcare buildings often have specific insurance requirements in their contract terms. The limits, additional insured wording and waiver of subrogation they ask for help determine what your policy needs to include. Send us the insurance section of the contract and we’ll help you find coverage that meets those requirements.
Workers’ Compensation
Moving hoses through stairwells, lifting portable extractors, working on wet floors and handling cleaning chemicals can all lead to workplace injuries. Workers’ compensation insurance pays an injured employee’s medical care and part of their lost wages.
Workers’ comp is required in 49 states once you have employees, although state laws differ on who counts as an employee. Texas lets employers choose not to have workers’ comp, but an employer without coverage loses its immunity from employee lawsuits. Ohio is different. Employers there buy coverage through the state’s own program, so we don’t quote workers’ comp in Ohio.
Workers’ comp is priced per $100 of payroll by class code. Report injuries within 24 hours. Claims reported that fast tend to cost much less, and fewer claims keep your experience modification rate near or below 1.0, which is the industry average.
Commercial Auto
Your van carries your crew and chemicals from one jobsite to another, often with a truck-mounted unit installed in the back. Personal auto policies commonly exclude business use, so a crash on the way to a 6 a.m. hotel job may not be covered by a personal policy. Commercial auto insurance is written for work vehicles and runs about $1,200 a year per pickup or van.
Check how your policy covers the truckmount. Some policies include permanently attached equipment as part of the vehicle’s coverage, while others require you to cover it separately or add it to an equipment policy.
Tools and Equipment Coverage
Portable extractors, air movers, dehumidifiers, hoses and wands are loaded and unloaded several times a day, making them easy to drop or steal. Equipment coverage, often set up as an inland marine policy, pays to repair or replace them while you’re moving between jobs or using them at a client’s property. For small contractors, it runs about $800 a year.
List the value of each machine when you apply. A policy written on an estimated total value might not provide enough coverage after a van break-in.
What Carpet Cleaning Insurance Does Not Cover
General liability for carpet cleaners has limits, and most surprises come from five exclusions:
Your own employees’ injuries. Those belong to workers’ compensation.
Your own vans, truckmounts and portable equipment. Those fall under commercial auto or equipment coverage.
Property in your care, custody or control. Rugs you take back to your plant are often excluded unless you add bailee’s customer insurance.
Redoing your own work. Re-cleaning a carpet you cleaned badly is a business cost, not a claim.
Pollution and mold. Pollution claims are typically excluded from standard general liability forms, and mold may be limited or excluded depending on the policy.
Exclusions vary by carrier and policy form. Ask to see the exclusions before you sign, so you find the gaps while you can still fill them.
Do you have a question? Call us 24/7.
Talk to a real agent, not a voicemail. Certificates of insurance the same business day, with bilingual support every day of the year.
Commercial auto and equipment coverage have fairly steady prices. General liability and workers’ comp move the most, because they follow your payroll, your services and the accounts you clean.
Policy Type
Policy Type
Carpet Cleaning Business
What It Covers
General Liability
About $871 a year, or $73 a month, per Insureon's 2026 data
Injuries and property damage you cause to others, such as a guest slipping on a damp hotel corridor or water reaching the ceiling of the floor below.
Workers' Compensation
Priced per $100 of payroll by class code
Medical bills and part of lost wages when a technician is hurt on the job.
Commercial Auto
About $1,200 / year per pickup or van
Accidents, theft and damage involving the vans that carry your crew and equipment.
Tools & Equipment
About $800 / year for small contractors
Theft of or damage to extractors, air movers, hoses and wands.
These ranges are typical, not quotes. Your premium depends on your state, revenue, payroll, vehicles and claims history, and every policy is subject to carrier underwriting.
Get Your Free Carpet Cleaning Insurance Quote
Have your payroll, vehicle list and any client contract requirements handy, and the quote moves faster.
Contractors Liability is an insurance agency, not a single insurance company. That lets us put several carriers’ prices side by side for your carpet cleaning business insurance.
Good Prices from Reliable Insurance Companies
We quote general liability with A-rated insurance companies. Carriers don’t all write carpet cleaning the same way, so we compare several before we send you options.
Nationwide Coverage
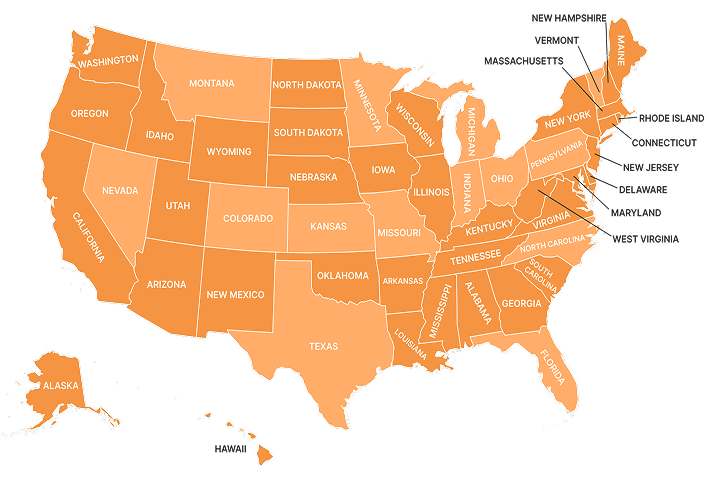
We’re licensed in all 50 states, so we can place coverage for carpet cleaning companies across the country. Rules change at the state line, especially for workers’ comp, and the state guides below cover licensing and comp requirements where your crews work.
Expert Guidance from Carpet Cleaning Insurance Specialists
Our agents ask the questions that change a carpet cleaner’s policy. Do you take rugs to a plant? Do you do flood extraction? Do you run a truckmount at hotels with underground parking? How many of your contracts require additional insured status? The answers decide which endorsements you need, and you can go through them with an agent in English or Spanish.
Fast and Simple Claims Process
The insurance company pays the claim, but you don’t have to handle it alone. Call us when something goes wrong and we’ll help you report it to the carrier. Take photos of the area and save your job notes the same day. A well-documented claim moves faster.
Flexible Payment Plans
Cleaning work can be seasonal, and cash flow can swing from month to month. That is why we offer different ways to pay.
You can pay your premium by debit card, credit card or check, whichever works best for your business.
Statewide Contractor Insurance Information
Insurance requirements for service businesses vary from state to state. Explore our state guides for general information on the policies contractors need in each state, including licensing and workers’ compensation rules.
Two companies in the same city can pay very different premiums for the same commercial carpet cleaning insurance limits. A quote built on your accounts and payroll is the only number that fits your business, and carriers look hardest at the following.
Your claims history:
A clean three-year record usually earns better rates. A new company with no history may pay more than an established one with the same record, because the carrier has nothing to price from.
The services and clients you serve:
Water damage restoration, rug plant cleaning and accounts like hotels and healthcare facilities usually price higher than routine office carpet maintenance.
Your vehicles and equipment:
Each van, truckmount and driver adds to your commercial auto and equipment premiums. Drivers with clean records help.
Where you operate:
Premiums change by state and city, based on local claim costs and the legal climate.
Carpet Cleaning Insurance Endorsements and Add-Ons
A base general liability policy leaves a few gaps that show up on commercial carpet jobs. Bailee’s customer coverage protects customers’ rugs and furniture while they’re at your plant or in your van. Hired and non-owned auto covers you when a technician drives a personal car to a job site.
Commercial clients and property managers often ask to be added as additional insured, sometimes with a waiver of subrogation, and larger contracts may need limits above $1 million through a commercial umbrella. If your crew locks up client buildings after hours, ask your agent whether a janitorial bond makes sense for your contracts. A janitorial bond reimburses the client if an employee steals from the premises. Tell us which services you sell and which clients you work for, and we’ll match the add-ons to your commercial carpet cleaning insurance.
Here’s What Contractors Think
Frequently Asked Questions
Here are common questions about carpet cleaning insurance.
What does carpet cleaning insurance cover?
For a commercial carpet cleaning company, it’s usually several policies working together. General liability covers injuries to your clients’ employees and guests and damage to their property. Workers’ comp covers your technicians. Commercial auto covers your vans, and equipment coverage protects your machines. Exact coverage depends on the carrier and policy.
Does general liability cover rugs I take back to my shop?
Usually not. Most general liability policies exclude property in your care, custody or control, and a rug sitting at your plant fits that description. Bailee’s customer coverage fills the gap. Add it before you take in the first rug.
Do I need commercial auto insurance for my carpet cleaning van?
A personal auto policy may deny a claim if the crash happened during business use, such as driving to a client’s building. Commercial auto insurance is written for work vehicles and runs about $1,200 a year per van. If you run a truckmount, ask how the mounted unit is covered.
Does carpet cleaning insurance cover my employees?
General liability doesn’t. Workers’ compensation does, and 49 states require it once you have employees. Our workers’ compensation page explains how it’s priced.
Will commercial clients ask for a certificate of insurance?
Expect it. Property managers, facility managers and general contractors want a certificate of insurance before you start, and many ask to be listed as additional insured. We issue a certificate for each client, usually the same business day.
We’ve collected all the most useful things in our e-books
Just read and in 30 minutes you will know everything about insurance.