General liability insurance protects contractors from claims involving third-party bodily injury, property damage, and certain advertising injuries. It can help cover legal costs, settlements, and other expenses for covered claims.
A general liability policy may be required by a client, general contractor, licensing authority, or contract before work begins. Coverage limits and requirements vary by project and location.
General liability insurance protects contractors from claims involving third-party bodily injury, property damage, and related legal costs. For example, if a client or other third party is injured at a job site or a contractor damages someone else’s property, general liability insurance may help pay for covered claims.
Contractors face these risks on every job, even when they take steps to prevent accidents. A single injury or property damage claim can result in medical bills, repair costs, and legal expenses. General liability insurance helps protect the contractor’s business from these costs when they fall within the policy’s coverage.
General liability insurance is often required by clients, contracts, or licensing rules. Coverage requirements vary by state and by project, so contractors may need specific policy limits to start or continue work. ContractorsLiability.com specializes in providing affordable and reliable general liability insurance to keep your business safe.
General liability insurance protects your business from claims related to property damage, bodily injury, and more. An essential benefit of this coverage is that it includes legal defense costs, such as attorney fees, if your business is sued over a covered claim. Here’s a breakdown of what general liability insurance typically covers:

General liability insurance can cover claims involving bodily injury caused by your business operations or products.
Example: A person trips over your tools while you are installing flooring and is injured.
This coverage can apply to certain claims involving libel, slander, or misuse of client images.
Example: A contractor uses your client’s home in marketing materials without permission, and the client files a lawsuit
Medical payment coverage can pay for certain medical expenses when someone is injured on your business premises.
Example: A client falls and injures themselves while visiting your office.
Coverage can apply to claims involving damage to a client’s or another third party’s property caused by your business operations.
Example: An employee accidentally damages a client’s vehicle while installing a garage door.
This coverage can apply when your business causes certain types of damage to a property you rent.
Example: A propane tank leak from your roofing business causes a fire in a rented building.
Coverage can apply to certain advertising injury claims, including allegations of copyright infringement, libel, or slander.
Example: Your business uses a protected brand name in an advertisement without proper authorization and faces a claim.
General liability insurance can cover several types of third-party claims to keep your business protected from everyday risks and potential lawsuits. Coverage depends on the policy terms, limits, and exclusions.
Talk to a real agent, not a voicemail. Certificates of insurance in under 4 hours, with bilingual support every day of the year.
While General Liability Insurance offers necessary protection, it’s important to understand what it does not cover. Here are some situations where this general liability insurance policies won’t provide coverage:
Injuries to your employees are not covered by general liability insurance. These are handled by workers’ compensation insurance. For example, if an employee falls off a ladder and gets injured, it won’t be covered under general liability.
Errors or omissions in professional advice or services are generally not covered bby general liability insurance. Professional liability insurance, also called errors and omissions insurance, can provide coverage for claims arising from advice, recommendations, or professional services that you give.
General Liability Insurance does not cover accidents involving your business vehicles. Instead, commercial auto insurance can protect your business vehicles against vehicle-related claims.
Most general liability policies do not cover punitive damages. These are financial penalties a court may order to punish wrongful conduct and discourage others from doing similarly. For example, a contractor knowingly ignores a serious safety hazard, and a court awards punitive damages because the conduct was considered especially reckless.
Damages resulting from intentional actions, such as an employee deliberately damaging property, are not covered by general liability insurance.
Faulty workmanship or poor-quality work, often referred to as the “workmanship” or “warranty” exclusion, is not covered. For example, if the paint you applied starts peeling due to improper preparation, this would not be protected by general liability insurance.
The cheapest general liability insurance policy may be enough for some contractors, but a lower price does not mean that the policy is suitable for your business. A policy with lower limits or fewer covered risks may cause you to pay more out of pocket for a claim.
The cost of coverage should be considered with the policy limits, coverage, exclusions,deductible, and requirements of your contracts or clients. A policy that meets your business needs at a reasonable price can provide better value than choosing based on premium alone.
General liability insurance is crucial for protecting your business from costly lawsuits and accidents. It covers legal fees and damages if a third party sues you for property damage or bodily injury, preventing significant financial loss.
You need a policy if a general contractor, a city permit office, a landlord or a state licensing board asks you for a certificate of insurance, if you bid on commercial or residential jobs, or if you hire subcontractors whose work you could be held responsible for. A sole proprietor with no employees needs it as much as a crew of twenty, because the size of a third-party injury claim is not scaled to the size of the business.
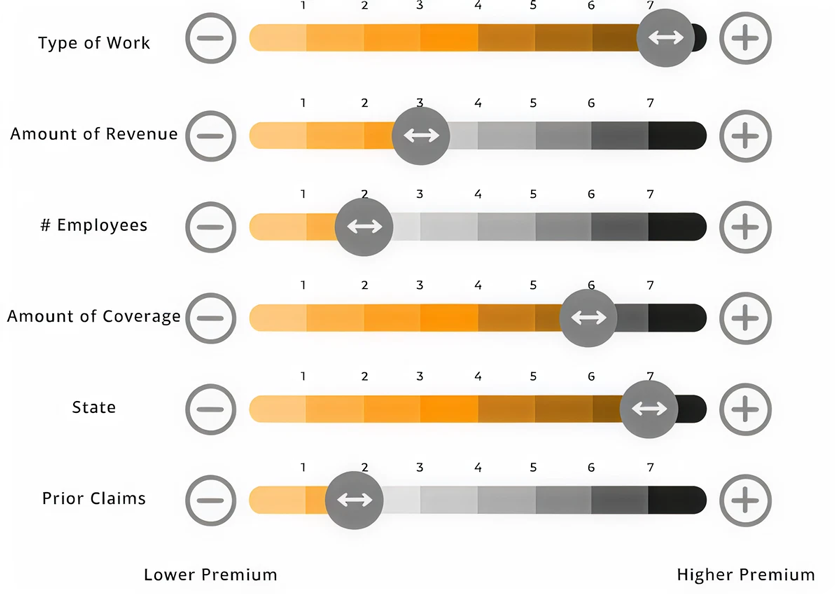
Several factors can affect the cost of general liability insurance. These include
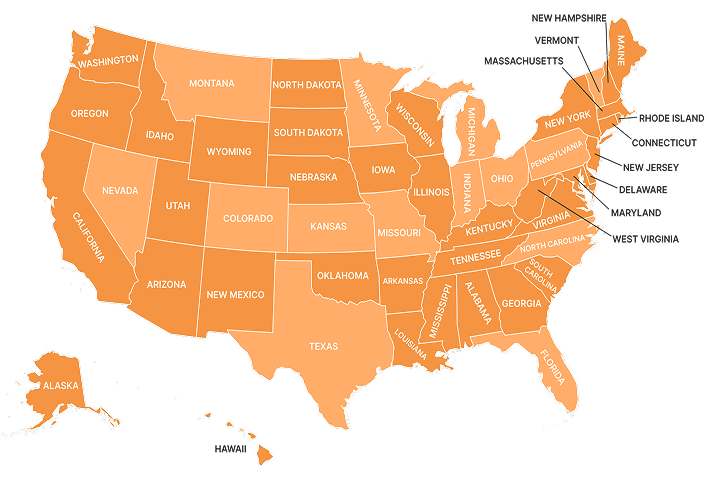
General liability insurance costs vary by state. The table below shows the five states with the highest average annual costs and the five states with the lowest. Washington, D.C. is included because it also appears among the highest-cost locations in the data.
| State | Annual average |
|---|---|
| California | $2,284 |
| District of Columbia | $2,206 |
| New York | $2,157 |
| Massachusetts | $2,027 |
| New Jersey | $1,916 |
| Montana | $1,139 |
| Iowa | $1,135 |
| South Dakota | $1,088 |
| Mississippi | $1,074 |
| West Virginia | $1,041 |
Source: MoneyGeek data, updated August 17, 2026.
These figures represent average annual costs from MoneyGeek’s data and are not quotes for individual contractors. Your actual premium can vary based on your trade, revenue, coverage limits, location, and claims history.
A client, city, or landlord may require your business to add them as an additional insured on your general liability policy. An additional insured receives certain coverage under your policy for claims related to your work, subject to the policy terms and endorsement.
For example, a general contractor may require a subcontractor to name the general contractor as an additional insured before work begins. A landlord may make the same request as a condition of a lease.
A certificate of insurance (COI) can show that the required coverage is in place and may list the additional insured. The certificate itself does not provide coverage or change the terms of the insurance policy.
Contractors who regularly need to add clients or other parties to their policy may have a blanket additional insured endorsement. This endorsement can extend additional insured status to parties that meet its requirements, often when a written contract requires it. Depending on the policy, there may be an additional charge for this endorsement.
A blanket endorsement can reduce the need to request a separate endorsement each time a qualifying client or other party requires additional insured status. The exact coverage and requirements depend on the policy and endorsement.
An additional insured endorsement adds another person or organization to your general liability policy for certain claims related to your work. Clients, general contractors, property owners, and other parties may require this before you begin a project.
Different endorsements provide different types of additional insured coverage. The endorsement required can depend on your contract and whether coverage is needed for work that is still in progress or has been completed.
The endorsement you need depends on who must be covered, whether the work is ongoing or completed, and what your contract requires. Four common endorsements for contractors are CG 22 94, CG 20 10, CG 20 33, CG 20 37, and CG 20 38.

In the last few years, insurance carriers are regularly adding the CG 22 94 endorsements to the commercial general liability policy to exclude losses arising out of subcontractor-caused damage to a contractor’s work. The theory behind the CG 22 94 endorsements is that the damage caused by a subcontractor’s work should be the responsibility of the General Contractor as a business loss and not a loss covered by the General Contractors General Liability Insurance Policy.
A number of General Liability carriers that insure home builders and remodelers have added this exclusion. As a result, this exclusion results in a substantial reduction in coverage as compared to prior policies.

The CG 2010 is commonly used to provide additional insured coverage to a person or business for certain claims for ongoing work. This endorsement is commonly used when a contract requires additional insured coverage while work is being performed. Once the work is complete this endorsement terminates.
For example, you are installing kitchen cabinets in a customer’s home. A cabinet falls and damages the customer’s countertop. If the general contractor hired you and is named as an additional insured under your policy, your insurance may help cover a claim against them related to the damage, subject to the policy terms.
The CG 20 37 endorsement can provide additional insured coverage for certain claims that come from completed work. Completed operations refers to work that has been finished, rather than work still in progress.
For example, a subcontractor finishes installing a roof, but a problem with the work later causes property damage. If the general contractor was properly added as an additional insured for completed operations, the endorsement may provide coverage.
The specific endorsement required depends on the contract and the coverage being requested. Contractors should review the additional insured requirements in their contracts with their insurance agent before work begins. CG 20 37 is commonly used with CG 20 10 when both going and completed operations are required.
The CG 20 33 endorsement can provide additional insured status to qualifying people or businesses without naming each one individually on the endorsement during ongoing operations. It generally applies when a written construction agreement requires the contractor to add that party as an additional insured.
For example, you do work for several general contractors. Each contract requires you to add the general contractor to your insurance. If the contracts meet your policy’s requirements, CG 20 33 may provide additional insured coverage without needing a separate endorsement for each general contractor.
The endorsement does not automatically cover everyone the contractor works with. The contract, policy wording, and endorsement requirements must be satisfied.
The CG 22 94 endorsement removes the subcontractor exception from the “damage to your work” exclusion. As a result, certain property damage to your completed work may be excluded even when a subcontractor performed the work or caused the damage.

A 1099-NEC is an IRS form that businesses use to report payments made to independent contractors. This by definition makes anyone who receives money that is classified as 1099 income not an employee of the party issuing the 1099. However, receiving a 1099 does not automatically make someone an independent contractor.
For contractors, hiring subcontractors can also affect insurance costs. General liability and workers’ compensation insurers may review subcontractor payments during a premium audit. If a subcontractor cannot prove they had the required insurance while working for you, the insurer may count some or all of those payments when calculating your premium. This can increase your premiums.
To help avoid unexpected charges, ask subcontractors for certificates of insurance (COIs) before work begins. Check that their coverage meets your policy and contract requirements, and keep the documents for your insurance audit. The exact requirements vary by insurer, policy, and state.
There are two types of General Liability policies:
General liability policies can be written on a claims-made or an occurrence basis. The main difference is when the policy provides coverage for a claim:
A claims-made policy generally covers claims made while the policy is active. An extended reporting period may provide additional time to report certain claims after the policy ends.
Example: A claim is made on March 1, 2026, after a claims-made policy expires on December 31, 2025. Unless an applicable extended reporting period or other provision applies, the expired policy may not respond to the claim.
An occurrence policy generally covers injuries or property damage that happen while the policy is active, even if the claim is made after the policy ends. Most general liability policies are written on an occurrence basis.
Example: A customer is injured at a contractor’s job site on October 30, 2025, while the policy is still active. The customer does not file a claim until March 1, 2026, after the policy has expired. If the claim is covered, the 2025 policy can respond because the injury occurred during that policy period.
The cost depends on factors such as the type of work, business revenue, number of employees, coverage limits, location, and claims history. In 2026, average general liability costs vary by state, but a contractor’s actual premium may be higher or lower based on the details of the business.
General liability insurance requirements vary by state, contract, project, and client. A client or general contractor may require proof of coverage before work begins. Some licensing rules may also require contractors to carry specific coverage or limits.
General liability insurance can cover claims for third-party injuries, property damage, and certain advertising injuries. It may also help pay legal costs for covered claims. The policy limits and exclusions determine what is covered.
A contractor can ask their insurance company to add a client or other party to the policy as an additional insured. This can give that party certain coverage under the contractor’s policy. The contract and policy determine who can be added and what coverage they receive.
The CG 20 33 endorsement is a blanket additional insured endorsement for ongoing operations to qualifying people or businesses without naming each one individually on the endorsement. The endorsement does not automatically cover everyone the contractor works with. The contract, policy wording, and endorsement requirements must be satisfied.
Just read and in 30 minutes you will know everything about insurance.