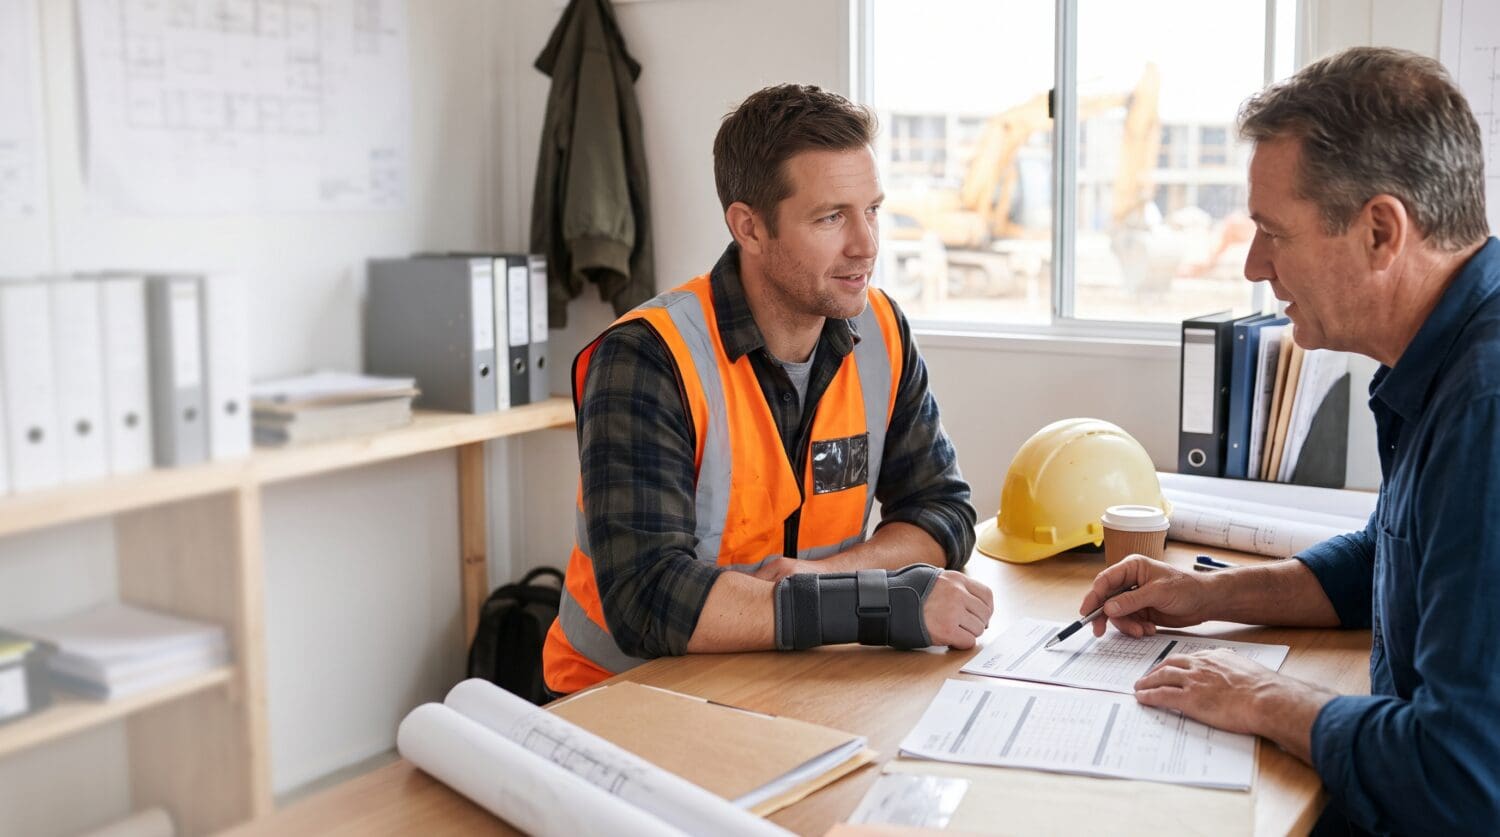

You’ve bought workers’ comp for your construction crew. Now you’re on a jobsite, helping move a stack of lumber, when you hurt your back. Your crew has coverage for work injuries, but what about you?
Can a business owner get workers’ comp? That’s a fair question to ask. Many can, but owning the company doesn’t mean you’re covered by its policy. At Contractors Liability Insurance, we help contractors sort out these kinds of coverage questions.
Plenty of business owners still work with their crews. A roofer might climb onto a roof to check repairs. A plumber might spend the morning fitting pipes before heading out to quote the next job. If an injury puts you out of work, you could lose the income you rely on to run your business.
The good news is that many owners can get workers’ comp for themselves. The process can be different from buying it for employees, though. We’ll explain who can qualify, what state rules mean for builders, and how to check your own coverage before an accident happens.
Can a Business Owner Get Workers Comp?
Yes, a business owner can get workers’ compensation for their own work-related injuries in many states, but they must be included in the coverage. Some owners are covered under state law, while others must choose to be included. The rules vary by state and business structure.
If you’re covered, workers’ comp can pay medical bills and replace part of your lost wages after a jobsite injury. Having a policy for your employees doesn’t always mean you’re covered too. Ask your insurance agent to confirm your own coverage before your next job starts.
Which Business Owners Can Get Workers’ Comp?
The first thing to check is your business structure. Two contractors doing the same job can face different rules if one is self-employed and the other runs an LLC. Here’s how the main types of ownership work.
Can a Business Owner Get Workers’ Comp Without Employees?
Yes, in many states. Say you’re a carpenter who takes on home repairs alone. You don’t have any staff, so you may have no legal duty to buy workers’ comp. Still, you can face the same risks as any employee. One bad fall could leave you unable to work for months.
Many states let sole proprietors buy coverage for themselves. New York, for example, allows a sole proprietor with no employees to choose workers’ comp. In California, the policy must clearly include the owner, or the insurer must add an endorsement. That’s a change to the policy that confirms who’s covered. Don’t assume a standard policy includes you.
Can a Business Owner Get Workers Comp Through an LLC?
Some states let LLC members choose to be covered. Others treat members as covered workers unless they meet the rules for an exemption. Partners can face their own set of rules too.
Picture two friends who own a remodeling company. One runs the office, while the other spends most days working with the crew. Both should tell the insurer what they do and ask how they’re listed on the policy. Their job duties can affect the price, but their owner status can affect whether they receive benefits at all.
What About Corporate Officers?
A corporate officer may be the president of the business and still spend every morning on a jobsite. Depending on state law, that person may be included in workers’ comp or allowed to seek an exemption. An exemption means the owner is left out of the coverage that would otherwise apply.
It’s easy to overlook this if you changed your business structure or signed an exemption years ago. Check your status again before taking on more site work. If you’re exempt, don’t assume you can claim workers’ comp when you get hurt.
Do Contractors Have to Cover Themselves?
This varies across the US. In some states, a solo contractor can choose coverage, but other states have stricter rules for construction, even when a business is small. Your trade and the people working for you can change what the law requires.
New York
New York lets sole proprietors without employees choose coverage for themselves. Partners and LLC members can also opt in. If you hire workers, though, your duty to cover them is a separate issue. The state’s construction rules can also affect how subcontractors are treated.
The New York Workers’ Compensation Board explains which business owners can choose coverage and how the rules apply to independent contractors working on construction projects in the state.
Florida
Florida requires construction employers with one or more employees to carry workers’ comp. This count includes corporate officers and LLC members who aren’t exempt. Certain owners can apply for an exemption if they meet the state’s rules. An approved exemption means that owners can’t receive workers’ comp benefits under it.
California
In California, a sole proprietor who wants their own workers’ comp benefits must be named in the policy or added by an endorsement. Some licensed construction trades also face special insurance rules, even with no employees. Check your license class rather than assuming every solo trade follows the same rule.
If you take projects in more than one state, tell your agent where you’ll be working. And if you employ a crew, our article on working without workers’ compensation explains the risks of missing required coverage.
What Does Workers Comp Pay for a Covered Owner?
Once you’re included, the policy may pay the same main types of benefits offered to other covered workers. The injury must qualify under the state’s rules, and you must be covered when it happens.
Medical Care After a Jobsite Injury
Suppose you’re laying tile and cut your hand badly with a tool. If the claim is covered, workers’ comp can pay for care such as a doctor’s visit, surgery, or therapy. Covered work illnesses may qualify too. The care and claim rules differ by state, so follow the steps your insurer gives you after an injury.
Lost Wages and Time Away From Work
Now imagine you own a framing business and break your leg on site. You can’t do your usual work for weeks. Workers’ comp may pay part of your lost wages while you heal, subject to state limits. Some injuries may also qualify for disability benefits or help with a return to work.
This is one reason to ask how your pay is recorded. A salary and an owner’s draw aren’t always treated the same way. Your insurer needs the right details to work out the premium and any wage benefits. Coverage won’t pay all your business bills while you’re away, so think about how the company would run without you.
Does a Ghost Policy Cover the Business Owner?
Usually, no. A ghost policy is often used by a one-person business that needs proof of workers’ comp but has no covered employees. The owner is excluded, so the policy doesn’t provide benefits for that person’s own job injury.
How Ghost Policies Work for Contractors
Say you’re a self-employed drywall installer. A general contractor asks you for a certificate of insurance before you can start. You buy a ghost policy and send over the certificate. If you later hurt your shoulder lifting drywall, that policy won’t pay your injury claim if you’re excluded.
What If You Want Coverage for Yourself?
A certificate shows policy details. It doesn’t turn an excluded owner into a covered worker. Ghost policies aren’t an option in every state, and some project contracts may call for more than proof of a policy.
Our article comparing ghost policies and standard workers’ comp goes into the differences. If you want injury benefits for yourself, ask for coverage that includes you.
How Much Does Workers’ Comp Cost for a Business Owner?
There’s no flat price for owner coverage. Your premium will vary based on your business, the work you do, and how your insurer rates the risk. Here’s what can affect the cost.
Your Trade and Daily Work
Insurers use job class codes to group work by risk. A roofing contractor who spends most days working at height may pay more than a construction business owner who works mainly in an office. Your state and the type of work you do will both affect your rate.
Your Payroll and Claims History
Adding yourself to a workers’ comp policy can raise the premium. Some states use a set payroll figure for covered owners, even if they don’t take a regular salary. Your past claims may affect the price too, so two contractors doing similar work could receive different quotes.
Comparing Workers’ Comp Quotes
General rate charts can give you an idea of costs, but they won’t tell you what you’ll pay for your own coverage. Tell your insurer how often you’re on site and what tasks you do, then check that each quote includes you as a covered worker. A cheaper policy won’t help much if you’re left out!
Our workers’ comp guide for contractors explains more about the factors behind insurance premiums.
How to Get Workers’ Comp as a Business Owner
If you want coverage for yourself, start before your next job gets underway. You may be able to add yourself to a policy you already hold, or you may need to buy a new one. Here are three steps to take with your insurance agent.
Step 1 – Confirm Your Owner Status
Your business structure and state rules will help determine how you can get coverage.
- Tell your agent if you’re a sole proprietor, partner, LLC member, or corporate officer.
- Ask if state law includes you, lets you opt in, or allows an exemption.
- If you’ve signed an exemption, find out how to change your status. You may need to complete a form or update your policy.
Step 2 – Describe the Work You Do
Your insurer needs a clear picture of your role to assess the risks and price your coverage.
- Explain what you do during a typical working week, including any hands-on work at job sites.
- Provide details about your trade, payroll, past claims, and where you work.
- Be clear about how often you carry out physical work, even if you spend most of your time managing the business.
Step 3 – Check Your Policy Before Work Starts
Before heading onto your next jobsite, confirm that your policy includes you as a covered worker.
- Ask for written proof that your owner coverage is in place, including its start date.
- Check whether any exclusions or exemptions affect your coverage. A certificate of insurance alone may not show if you’re included.
- Ask how your earnings are handled and what benefits you could receive after a covered injury.
We can help you compare workers compensation coverage for your trade and review the owner details that need attention.
If you also carry general liability insurance, keep in mind that it serves a different purpose. It won’t replace workers’ comp benefits for your own work injury.
Can a Business Owner Get Workers Comp After an Injury?
Yes, a business owner can claim workers’ comp after an injury if they were covered when the accident happened. But if you were excluded from the policy, buying coverage after the injury won’t make that past accident eligible for benefits.
If you’ve already been hurt on a jobsite, contact your insurer or state’s workers’ comp board to check your coverage status on the date of the accident. Don’t assume you’re covered because your business has a policy. Your eligibility will be based on state rules and whether you were included in the coverage when you got hurt.
Check Your Workers’ Comp Before Your Next Job
So, can a business owner get workers comp? Yes, many can.
We’ve covered who can qualify, how state rules affect coverage, and why some owners may be left out of their own policy. The key point is that having workers’ comp for your crew doesn’t always mean you’re covered too.
Before your next job starts, check if you’re included in your policy. If you’re not, ask your agent what you need to do to get covered. It’s much better to sort this out now than face a nasty surprise after an injury.
At Contractors Liability Insurance, we help builders and trade owners find coverage that fits their work. If you’re unsure about your own protection, talk to our team about your workers’ comp options.
Frequently Asked Questions
Can a business owner get workers’ comp without taking a salary?
Often, yes. Some states use a set payroll amount to price owner coverage, even if you take owner’s draws rather than wages. Tell your agent how you pay yourself so they can check the correct rules.
Does workers’ comp cover an LLC owner who works on site?
It can. Some LLC members are included under state law, and others must choose to join the policy. Your job duties alone don’t prove you’re covered. Ask your agent to check your owner status.
Can I exempt myself from workers’ compensation and still cover my employees?
In some states, eligible owners can be excluded while the business keeps coverage for its workers. You must meet the state’s rules and follow the right process. An owner who is exempt won’t get benefits for their own injury under that exemption.
Will workers’ comp cover an injury that happened before I bought the policy?
No, a new policy doesn’t cover a past injury. If you had coverage on the date of the accident, you can ask the insurer to check the claim. Coverage and benefits follow the rules in force when you were hurt.