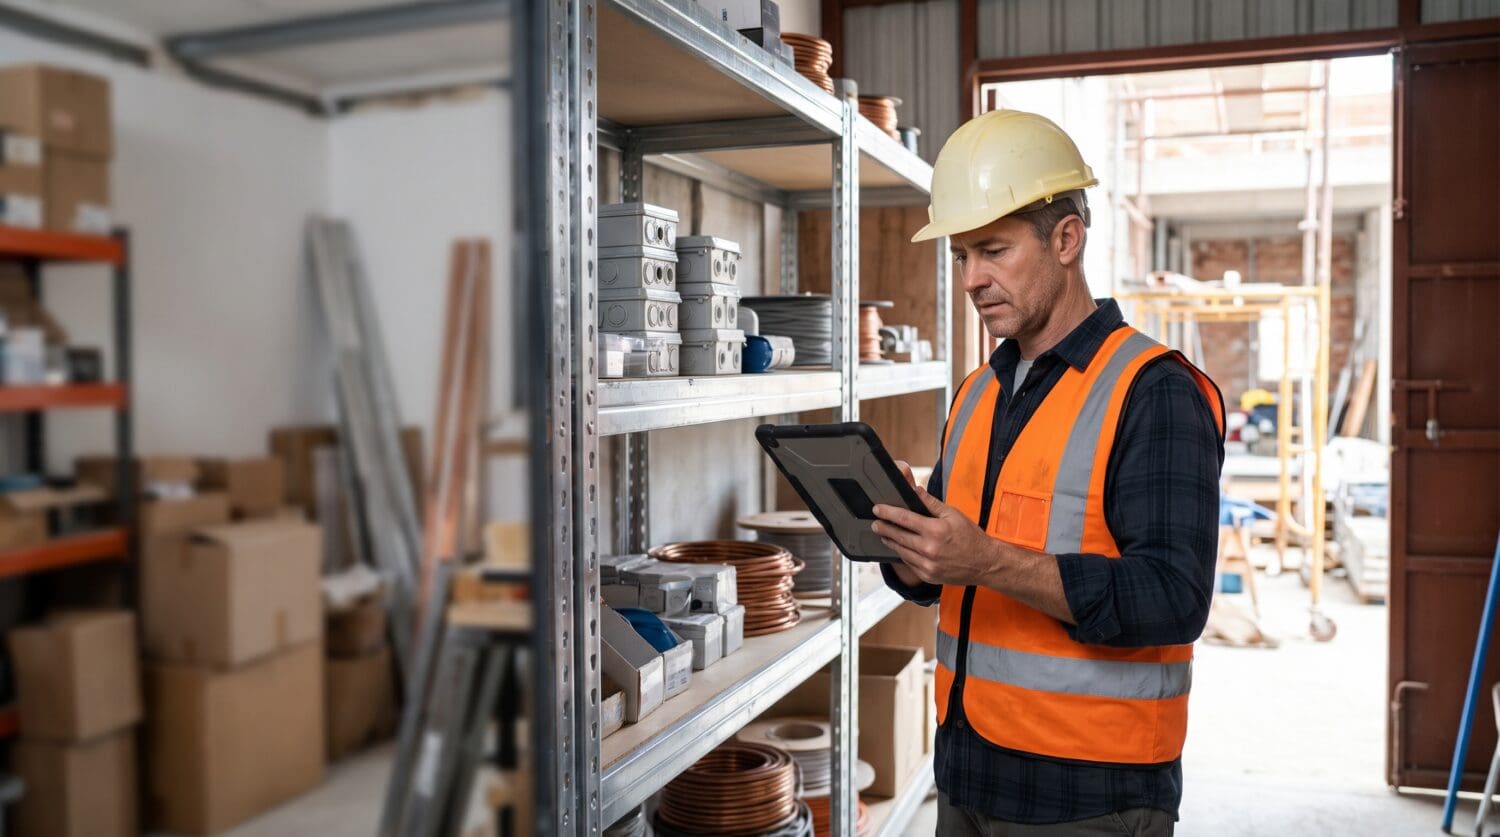
You arrive at a renovation site on Monday to find that several boxes of copper pipe have gone missing. The storage area was locked, and only a few crew members had access. So, does builders’ risk insurance cover theft if someone working on the project took the materials? Theft may be listed on the policy, but the person who took the supplies can change the answer.
At Contractors Liability Insurance, we help builders and contractors check what their project insurance will protect. A theft can force you to buy supplies twice and hold up the next trade. Your client still wants the work finished on time, and you may need new pipe before the insurer settles the claim. It’s harder still if the person responsible worked on site.
Builder’s risk often covers stolen building materials, but it commonly excludes theft by employees. The rules can extend to subcontractors too. We’ll explain how these exclusions work, which property may be covered, and what to do if materials disappear during a job.
Does Builders Risk Insurance Cover Theft by Workers?
Does builders’ risk insurance cover theft by people on your crew? Usually not.
Many policies cover stolen project materials taken by outside thieves but exclude theft by the insured’s own employees. They may also exclude dishonest acts by subcontractors or people trusted with the supplies. The final answer comes from your policy and the facts.
Here’s how common cases may be treated:
- An outside thief steals materials: The loss may be covered if theft is included and the property meets the policy terms.
- Your employee takes materials: Employee theft is commonly excluded, even if the materials would otherwise be insured.
- A subcontractor or their worker steals: Coverage may be excluded under rules for dishonest acts by contractors or other trusted people.
- Materials are missing with no clear cause: The insurer may need proof of theft. Some policies exclude losses known only through a stock shortage.
Listing theft on a policy doesn’t mean every missing item is covered. The person who took it and the kind of property can change the claim.
Why Is Theft by Employees Often Excluded?
Builder’s risk is property insurance for construction work and materials. It may pay for a covered theft by someone outside the project.
Worker theft is different. Many policies have a dishonest acts exclusion that blocks payment for theft by certain workers or trusted people.
Workers Who Are Part of Your Business
Imagine you own a plumbing company and an employee takes new fittings from the project store to sell. If your builder’s risk policy excludes employee theft, you can’t claim for those fittings under its usual theft cover. The fact that they were bought for the insured project doesn’t remove the exclusion.
Employee theft is a common exclusion. Each insurer may word the rule differently, so check your own policy.
Subcontractors and Temporary Workers
Say a general contractor brings in a crew to fit electrical systems. A worker on that crew takes cable from the site. That person isn’t employed by the general contractor, but the loss may still be excluded.
Some forms exclude dishonest acts by subcontractors and their staff. Others name people trusted with the property, which can include hired workers. Someone who isn’t on your payroll may still fall under an exclusion.
Ask your agent how the policy treats other trades on site. Our article on who is covered for theft at a construction site explains the roles involved.
Who Stole the Materials and Will the Policy Pay?
Two thefts may look the same until you find out who took the property. Here’s how the cause of a loss can affect cover.
| Who May Have Taken the Property? | How Builder’s Risk May Respond |
| Outside thief with no link to the job | Theft may be covered if the policy insures the items and the site meets its theft terms. |
| Employee of the insured business | Often excluded as an employee’s dishonest act. |
| Subcontractor or a member of their crew | May be excluded under contractor or entrusted-person rules. Check the exact wording. |
| Owner, partner, or other insured person | Dishonest acts by an insured person are commonly excluded. |
| Unknown person, with materials missing | The insurer will need facts that support a theft claim. An unexplained shortage may not be enough. |
The policy terms and evidence of the theft will shape the decision.
What If You Can’t Prove Who Took Anything?
You may know that 20 boxes were delivered, yet find only 14 when the crew starts work. That doesn’t prove a theft occurred. A count can be wrong, supplies may have been moved, or another trade may have used them with approval.
Check delivery notes and who had access. Some policies exclude an unexplained shortage with no proof of theft. Save footage and records for the insurer.
Does Builders Risk Insurance Cover Theft of Materials and Tools?
Even with an outside thief, the type of property counts. The policy may treat copper pipe differently from a cordless drill.
Materials Going Into the Building
Does builders risk insurance cover theft of loose supplies? It can, but the policy may treat them differently from materials already installed. Lumber, wiring, and pipes meant for the finished building may qualify if they meet its terms.
Some policies need an extra form for loose supplies or have lower theft limits. Off-site storage may have its own rules. Our guide to the difference between builder’s risk and inland marine insurance explains how storage and travel can affect cover.
Who Owns the Materials and Who Is Insured?
The project owner may have paid for the supplies, but the contractor may be in charge of them. A builder’s risk claim can involve both. Check who is listed as an insured and whose financial loss the policy covers. A subcontractor should not assume the general contractor’s policy will pay for stolen supplies it owns. Ask for the details before materials arrive on site.
Tools and Equipment Used by Your Crew
A saw used on five jobs isn’t the same as the piping bought for one new house. Contractor-owned tools and mobile equipment often need their own policy, even if you keep them on an insured building site.
Tools and equipment cover (often sold as inland marine insurance) can help with theft at job sites or during travel. It may still exclude employee dishonesty. Our article on insurance for construction tools shows which policies may fit your gear.
What Happens After a Theft Claim?
If the insurer accepts a claim, limits and deductibles still apply. A deductible is the part of a covered loss you pay yourself.
Say an outside thief takes $12,000 of covered wiring. If the insurer agrees on that value and the deductible is $2,000, the payment could be $10,000. Other limits may change that figure.
If a worker stole the wiring and the dishonest acts exclusion applies, builder’s risk may pay nothing. A high coverage limit won’t remove that exclusion. The policy may cover damage from an outside break-in but still deny the stolen items if a listed exclusion applies. Keep the facts of the loss separate from guesses about the thief.
What Insurance Can Cover Theft by Employees?
Commercial crime insurance with employee theft cover can help a business after a covered dishonest act by one of its employees. You may also hear this called employee dishonesty insurance or fidelity coverage. It is separate from standard builder’s risk protection.
Ask if a crime policy covers project materials and temporary workers. Check subcontractors too. Their staff may not meet the policy’s definition of an employee, so get that part in writing.
A rejected builder’s risk claim won’t always qualify under crime cover. Its terms must fit the loss too. Review these options before work starts.
What Should a Contractor Do If Materials Go Missing?
Missing supplies can delay the next trade. Take these steps, even if you don’t know who is responsible.
Step 1 – Check the Site and Keep the Evidence
Check that the materials weren’t moved or used. Look at delivery receipts and take photos of the storage area. Save camera footage, and don’t accuse a worker without evidence.
Step 2 – Report a Suspected Theft
If you suspect theft, contact the police and ask for a report number. Tell the property owner or general contractor if your agreement calls for it. Give the police what you know without naming a suspect based on a hunch.
Step 3 – Contact Your Insurer
Tell your insurer what is missing and when you found out. Share your receipts, photos, and police report number. Ask what proof is needed and if the policy sets a claim deadline. Don’t wait for the police to finish their work before telling the insurer.
Step 4 – Keep the Project Moving Safely
Update your schedule and keep replacement invoices. Save any damaged locks until the insurer says they’re no longer needed. If you suspect a worker, handle the issue fairly and seek legal advice when needed. You can plan the next delivery without treating an open claim as a sure payout.
How Can Contractors Reduce Theft on Site?
Good records may help you spot missing supplies and support a claim. Start with areas where you store high-value items.
Control Access to Valuable Materials
Lock storage areas and limit access codes. Keep a record of who enters, and change codes when workers leave the project. If trades share a storage room, set clear rules for who can remove stock. Give each crew the access they need for their work.
Keep Track of Deliveries and Stock
Count supplies on arrival and note where they’re stored. Track use of high-value items so a missing box doesn’t go unseen for weeks. If the count doesn’t match, ask the team to check deliveries and use records first. You may find an error before it becomes a theft claim.
Check Theft Cover Before Work Starts
Ask about loose materials, off-site storage, and theft during delivery. Check how the policy treats staff and subcontractors, and review the project contract. Ask about after-hours site rules too. Some theft forms set extra conditions for loss at night, so it’s better to know them before you lock up.
Check Your Theft Coverage Before Materials Disappear
Does builders risk insurance cover theft by workers? Usually not when the loss is caused by your own employee. We’ve covered how theft by subcontractors is treated, which items may be insured, and what to do after a loss.
Before your next project, check access to materials and any dishonest acts exclusions. You’ll have a clearer idea of your cover before something goes missing.
At Contractors Liability Insurance, we help builders compare builders risk insurance for their projects. If you want to check theft limits or exclusions before work starts, talk to our team about your options.
Frequently Asked Questions
Does builders risk insurance cover theft by subcontractors?
It may not. Some policies exclude dishonest acts by subcontractors and their workers. Check how your policy defines contractors and people trusted with project materials.
Does builders risk insurance cover theft after hours?
It can, but some forms require guards or set other site security rules for after-hours theft. Check the policy and any theft endorsement before leaving materials on site overnight.
Does builder’s risk cover stolen tools?
Not always. Project materials and your own tools can be treated differently. You may need tools and equipment insurance for gear used across several jobs.
Can I claim if materials are missing but no one saw a theft?
You can report the loss to your insurer, but proof may be needed. Some policies exclude a stock shortage when there is no other evidence that a theft took place.
Does employee dishonesty insurance cover subcontractors?
Not automatically. Some crime policies cover certain hired workers, but subcontractor crews may fall outside the policy’s definition of an employee. Ask your insurer to check before work starts.