Get contractors insurance for your Texas business. Compare general liability, workers’ compensation, commercial auto, and other coverage for your work, employees, equipment, and projects.
Need help choosing coverage? Call (888) 973-0016 to discuss your insurance needs.

Contractors insurance in Texas helps protect construction businesses against certain liability claims, employee injuries, vehicle accidents, and damage to tools or equipment. The coverage your business needs depends on the work you do, whether you hire employees or subcontractors, the vehicles you use, and the contracts you sign.
Whether you are a general contractor, carpenter, concrete contractor, electrician, excavator, handyperson, plumber, or roofer, your insurance needs depend on contract requirements, follow jobsite rules, and the work you do.
Texas also has some rules that differ from other states. Private employers generally are not required to carry workers’ compensation, while commercial vehicles must meet state financial responsibility requirements. Public construction projects can have additional workers’ compensation requirements, and private contracts may require coverage limits that are higher than the state minimums.
Commercial vehicles must meet Texas’ minimum insurance requirements. Workers’ compensation has different rules because Texas allows most private employers to choose whether to carry it. Public construction projects are subject to additional requirements.
General liability, builder’s risk, inland marine, umbrella insurance, and higher commercial auto limits may also be required by a construction contract even when the state does not require the coverage for every contractor.
A certificate of insurance, or COI, is the document that shows your coverage is active. It typically shows the policyholder name, the carrier, policy types, limits, effective dates, and other core details. Many contractors are asked to send a COI before they can start work, enter a jobsite, or finalize a contract.
A COI shows that insurance is in place, but the certificate itself does not change the policy or create coverage. If a contract requires another party to be an additional insured, the appropriate policy endorsement provides that status.
A Texas general contractor with $100,000 in average revenues may pay around $122 per month for general liability insurance, although actual rates vary by business and location.
The estimates below show estimated monthly costs for a general contractor with $100,000 in annual revenue across selected Texas counties. The examples assume $100,000 in annual revenue and $1 million per occurrence with a $2 million aggregate limit. These estimates illustrate how local market conditions can affect premiums.
| County | Local market | Estimated Monthly Cost |
|---|---|---|
| Harris County (Houston) | Urban | $140 – $160 |
| Dallas County (Dallas) | Urban | $138 – $152 |
| Tarrant County (Fort Worth) |
Urban | $125 – $135 |
| Bexar County (San Antonio) |
Urban | $125 – $138 |
| Travis County (Austin) |
Rapid growth urban | $130 – $145 |
| Collin County | High-growth suburban | $120 – $130 |
| Austin County | Rural | $95 – $110 |
| Martin County | Oil-producing | $145 – $175+ |
| El Paso County | Mid-sized metro | $105 – $115 |
These figures are estimates, not quotes. Location can affect pricing, but insurers may also consider annual revenue, payroll, construction class, claims history, subcontractor use, vehicles, project type, coverage limits, and other underwriting factors.
Revenue is one factor insurers use when pricing general liability insurance. Contractors with higher revenue may pay more because they typically handle more projects and have greater overall business exposure.
The following estimates show how general liability insurance costs can change at different annual revenue levels.
| Annual Revenue | Estimated Annual Premium Range | Estimated Monthly Cost |
|---|---|---|
| $50,000 | $775 – $1,575 | $65 – $131/mo |
| $100,000 | $1,025 – $2,400 | $85 – $200/mo |
| $150,000 | $1,475 – $3,325 | $123 – $277/mo |
| $250,000 | $2,300 – $5,300 | $192 – $442/mo |
| $500,000 | $4,100 – $9,050 | $342 – $754/mo |
| $750,000 | $5,850 – $12,300 | $488 – $1,025/mo |
| $1,000,000 | $7,600 – $15,500 | $633 – $1,292/mo |
General liability insurance is essential for Texas contractors. General liability insurance protects the business when a third party claims that your work, operations, or business activities caused bodily injury or property damage.
For contractors, that can include a client tripping over materials at a jobsite, damage caused during active work, or a completed project that later causes harm. If a deck fails after installation and injures someone, or if your crew damages part of a client’s property during a renovation, general liability typically covers these claims.
This coverage is commonly requested before work begins. Project owners, property managers, landlords, and hiring contractors may require certain limits or policy features. General liability does not replace every other policy a contractor may need. Employee injuries, your own tools and equipment, and company vehicle accidents require separate coverage.
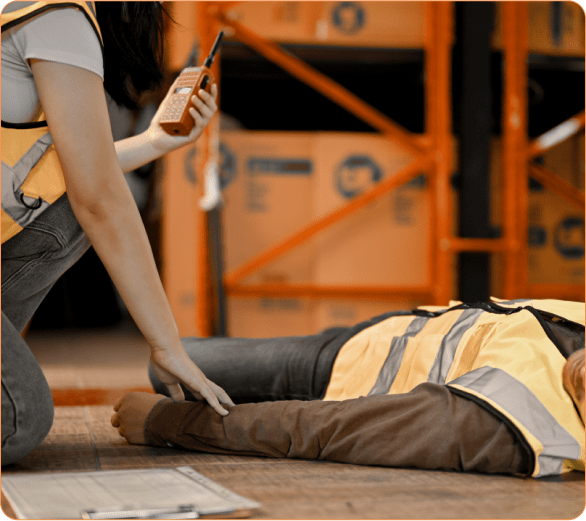
Texas is the only state in the United States that lets most private employers opt out of workers’ compensation insurance. Employers that carry coverage are called subscribers, while those that do not are non-subscribers. Around 31% of small private Texas employers with 1-4 employees are non-subscribers.
Going without coverage can expose your business to an injured employee’s lawsuit and financial damages that workers’ compensation would not cover. A policy can also help you meet insurance requirements for projects that require it.
Get a free workers’ compensation quote to find coverage for your contracting business.
Texas law does not generally require private employers to carry workers’ compensation, but a contractor may still need it for a specific project or contract.
Public construction projects have additional requirements. Government entities entering construction contracts must require contractors, subcontractors, and employees working on the public project to carry workers’ compensation coverage.
Private customers and general contractors may impose similar requirements through their contracts.
If a project requires coverage, going without it could mean missing out on the work. Check your contract requirements and get a quote before your next project.
Commercial auto insurance covers vehicles used in the business. For contractors, that may include pickup trucks, vans, service vehicles, or other automobiles used to move workers, tools, and materials between locations.
This policy includes liability coverage for bodily injury and property damage you cause in an accident. It can also include physical damage coverage for the business vehicle itself. Collision coverage applies when the vehicle is damaged in a crash. Comprehensive coverage can help pay for damage to your business vehicle from events other than a collision, such as theft, vandalism, fire, or certain weather-related damage.
Auto insurance is mandatory in the state of Texas, and this extends to commercial auto insurance. Texas law requires all motor vehicles, including vehicles used commercially, to carry minimum financial responsibility limits. These limits are known as the 30/60/25 coverage:
These are commonly referred to as the 30/60/25 limits. Requirements can be higher depending on the vehicle’s weight, passenger capacity, and the type of service it provides.
Driving a business vehicle without the required insurance can lead to fines and full out-of-pocket liability if you cause an accident. Because Texas is an at-fault state, the party responsible for an accident may be financially responsible for any resulting injuries or property damages. Without the required insurance, these costs could come directly out of the business owner’s pocket.
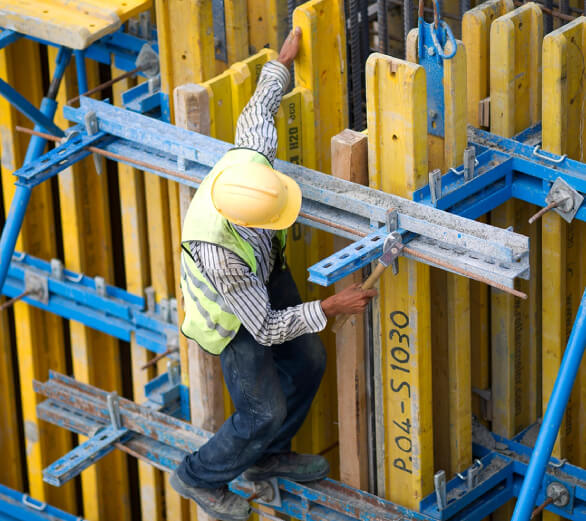
Builder’s risk insurance protects buildings and structures while construction is still in progress. In Texas, it can help cover damage to a structure under construction from causes such as fire, lightning, explosion, hail, vandalism, theft, and certain weather events (acts of God).
Depending on the contract and policy, it may include other stakeholders including property owners, lenders, general contractors, subcontractors, and design professionals tied to the work. Builder’s risk insurance focuses on the project property itself during the construction phase. This can include:
Some policies can be extended to cover scaffolding, building forms, or debris removal after a covered loss. The exact terms depend on the carrier and the job.
Inland marine insurance covers certain tools, equipment, materials, and other business property while they are being transported or stored away from your main business location.
Although it is not required by law, inland marine insurance is useful for contractors who move valuable property between jobsites or keep materials and equipment at temporary locations. A standard commercial property policy may not fully protect those items once they leave the insured premises. Theft, collision, and accidental damage during transit are among the losses this policy may help cover.
Commercial umbrella insurance gives a contractor extra liability protection after the limits of certain other insurance policies have been reached. If a large claim goes past the limit of general liability, commercial auto liability, or employer’s liability coverage, umbrella insurance may help absorb the amount above that limit, up to the umbrella policy maximum.
For a contractor, this extra layer can be valuable on larger jobs. A serious injury claim, major vehicle loss, or large property damage case can rise well past the limit carried on the primary policy, which can jeopardize a company’s financial stability.
Texas contractors may need several types of insurance depending on their work, employees, vehicles, contracts, and projects. While some coverage is required by law in certain situations, other policies may be required by a client or project contract. Going without the right coverage can leave your business responsible for costly claims and legal expenses.
Contractors Liability helps Texas contractors find insurance for their specific business needs. Whether you need general liability, workers’ compensation, commercial auto, builder’s risk, or other coverage, we can help you find a policy that fits your work and budget.
If you want to get the best coverage now, from the best carriers and at the lowest price, call us at (888) 973-0016 or click for a free quote. Our team can answer your ques
Get answers to your most common questions from Contractors Liability
Texas does not require every contractor to have the same set of insurance policies. Vehicles must meet state financial responsibility minimums, and workers’ compensation rules depend on the employer and project. Public construction contracts require workers’ compensation, while private clients may require general liability, higher liability limits, or other coverage before work begins.
Texas requires minimum financial responsibility limits for covered vehicles, but those limits are not necessarily the limits required for a contractor’s business. Commercial customers and construction contracts may require higher limits.
The cost of contractors insurance in Texas depends on the type of work, annual revenue, payroll, claims history, subcontractor use, and coverage limits. General liability insurance starts at about $65 per month for a contractor with $50,000 in annual revenue. Your actual price may be higher or lower depending on your business and coverage needs.
To get a quote, provide information about your business, the type of contracting work you perform, your annual revenue, payroll, subcontractors, and any vehicles or equipment you need to insure. You can request a free quote online or call (888) 973-0016 to discuss coverage options for your Texas contracting business.