Errors and Omissions Insurance

Errors and Omissions Insurance For Contractors

Errors and omissions insurance, also called E&O, pays the legal defense costs, settlements and judgments that follow a claim that your professional work was wrong, incomplete or late. For contractors it is the policy that responds to faulty workmanship on the work you performed, which a general liability policy does not cover. Compare carrier quotes in about 5 minutes and get same day coverage in most cases.

Contractor reviewing plans on a site that the E&O insurance covers.
Introduction
Professionals working independently face the risk of errors that may result in significant financial consequences. Errors and omissions insurance serves as a vital defense, ensuring that you and your business are protected from legal claims arising from professional services.
Did you know?

Contractors’ E&O coverage should not be confused with Contractors’ Professional Liability Insurance. Contractors’ Professional Liability Insurance is for contractors involved in construction management and design-build work.

Exploring Errors and Omissions Insurance for Professionals

Errors and omissions insurance is designed to cover the costs associated with claims of negligence, mistakes, or incomplete work. This type of insurance is especially valuable for freelancers, consultants, and small business owners who provide specialized services. It helps protect your reputation and finances by covering legal defense costs, settlements, or judgments related to professional errors.
Get an Errors and Omissions Insurance Quote Fast

Only 5 minutes of your valuable time. We can often get same day coverage.

What Does Errors and Omissions Insurance Cover?

E&O insurance offers comprehensive protection to professionals who may face legal challenges related to their work. The key coverage elements include:

Expert advice

Contractors E&O insurance covers faulty workmanship. If your completed work is damaged because it was performed incorrectly and you are held liable, the policy pays to repair or replace the substandard work and covers the legal defense against the claim. 

With just a general liability policy you are only covered for damage your work causes to a third party’s property, not for the cost of redoing your own work.

What Is Not Covered By A Contractors E&O Insurance?

A contractors E&O insurance policy specifically excludes liability for:

These are covered by your General liability insurance. It also does not cover you if you bid or estimate a job incorrectly, offer opinions to clients on contracts or agreements, just to name a few things that are not covered.

Construction crew with blueprints, the kind of crew general liability insurance covers.

Why is E&O Insurance Crucial for Small Business Owners?

Small business owners and freelancers often underestimate the impact of potential legal claims. Without errors and omissions insurance, even a small mistake could lead to a lawsuit, jeopardizing your financial security. Here’s why it’s critical:

Do you have a question? Call us 24/7.

Talk to a real agent, not a voicemail. Certificates of insurance in under 4 hours, with bilingual support every day of the year.

Certificate of Insurance

Update Coverage

Additional Insured

Billing

Address Change

Customer Service

Contractors Liability agent on a headset answering a general liability policy question.

Do Clients Require Proof of Errors and Omissions Insurance?

Many do. General contractors, property managers and commercial clients routinely ask for a certificate of insurance showing errors and omissions coverage before they award work, and some write a minimum limit into the contract. Carrying the policy protects the business from the cost of a negligence claim and keeps you eligible for the contracts that require it.

Errors and omissions claim covering repair of a contractor's faulty work.
Artisan contractor installing finished work covered by a contractors E&O policy.

Who Needs Contractors E&O Insurance?

Any artisan contractor who regularly installs work in or around a client’s property should carry a contractors E&O policy. Most GL Liability policies now state that faulty workmanship and defective construction are not an occurrence under the terms of the policy. As a result you will not have any coverage under your general liability policy. Even if faulty workmanship is covered there are usually exclusions that can leave artisan contractors with coverage gaps. If this happens you may end up paying out of pocket for repairs or replacement of your work.

Here’s What Contractors Think

Common Questions About Errors and Omissions Insurance

No, E&O insurance does not provide protection for intentional wrongdoing or fraud.
No, the policy only covers specific claims related to errors or omissions in your professional services, not general business risks like theft or property damage.
No, errors and omissions insurance only applies to claims directly related to the professional services you provide.
No, if the services were provided without necessary licenses or certifications, the policy will not offer protection.

Premiums depend on your trade, annual revenue, the policy limit you choose and your claims history. Most contractors can compare quotes from multiple carriers in about 5 minutes and often start coverage the same day. Insert the current verified premium range here before publishing.

General liability covers physical harm your business causes to other people or their property. Errors and omissions covers the financial consequences of the professional work itself being wrong, including faulty workmanship on the work you performed. Most contractors carry both, because neither policy responds to the other’s claims.

Cover of Contractors and Handyman Insurance guide e-book from Contractors Liability.
We’ve collected all the most useful things in our e-books

Just read and in 30 minutes you will know everything about insurance.

Contractors Big Icon

GET A FREE GENERAL LIABILITY QUOTE WITHIN MINUTES

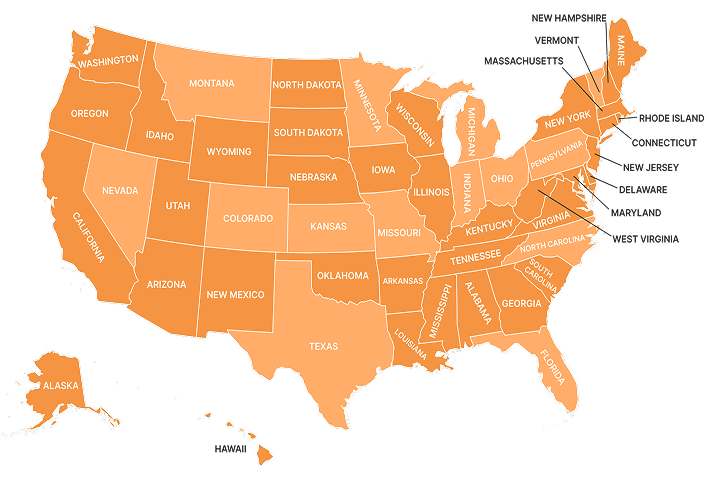
states-map image